Poland's Last KSeF Exemption Ends 1 January 2027 — What 'Digitally Excluded' Taxpayers Need to Know
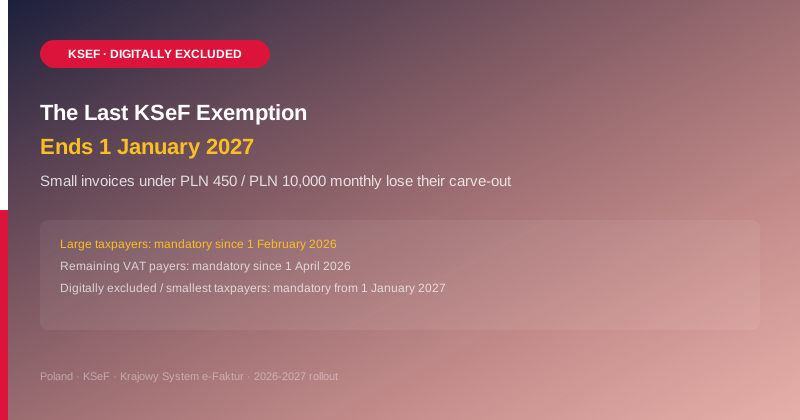
KSeF is already mandatory for large taxpayers (since February 2026) and most other VAT payers (since April 2026). The one remaining carve-out — for the smallest, "digitally excluded" businesses issuing invoices under PLN 450 — expires on 1 January 2027.
Poland's KSeF (Krajowy System e-Faktur) rollout has happened in stages, and the final one is now less than four months away. Here is exactly who is still exempt, and when that ends.
The Rollout So Far
- 1 February 2026: KSeF became mandatory for large taxpayers (roughly 4,200 businesses with 2024 turnover above PLN 200 million).
- 1 April 2026: The mandate extended to most remaining VAT-registered businesses, who must both issue and receive invoices through KSeF.
The Remaining Carve-Out: "Digitally Excluded" Small Taxpayers
A narrow exemption still applies to what the Ministry of Finance calls "digitally excluded" taxpayers — businesses whose invoices are small enough that the legislature judged a forced, immediate KSeF migration disproportionate. The thresholds are:
- Single invoices up to PLN 450 gross (roughly €100)
- Total monthly sales documented this way up to PLN 10,000 (roughly €2,300)
Businesses meeting both conditions can currently continue issuing simplified invoices and NIP-bearing cash-register receipts outside KSeF. Note that since 1 April 2026, a buyer generally cannot deduct VAT based on a receipt-with-NIP that falls outside this exemption band, so the carve-out is narrower in practice than it first appears.
The Deadline: 1 January 2027
From 1 January 2027, this last exemption disappears. Every remaining VAT-registered business — including the smallest, previously "digitally excluded" taxpayers — must issue invoices through KSeF. There is no further phase planned beyond this date under the current law.
Why This Matters Now
Businesses relying on this exemption often assume it is permanent, or confuse it with the separate 2026 no-penalty grace period the Ministry of Finance announced for early KSeF errors (which is unrelated and does not extend the 1 January 2027 deadline). If your invoicing volumes are small enough to have qualified for this carve-out, this is the point to start migrating: get a KSeF-integrated invoicing tool in place well before the new year, rather than in the final weeks of December.
Source
Comarch, "KSeF: National System of e-Invoices in Poland"; KSeFGPT, "Receipt with NIP after 1 January 2027 — the end of simplified invoices outside KSeF".