Poland Extends KSeF Penalty-Free Period Through the End of 2027
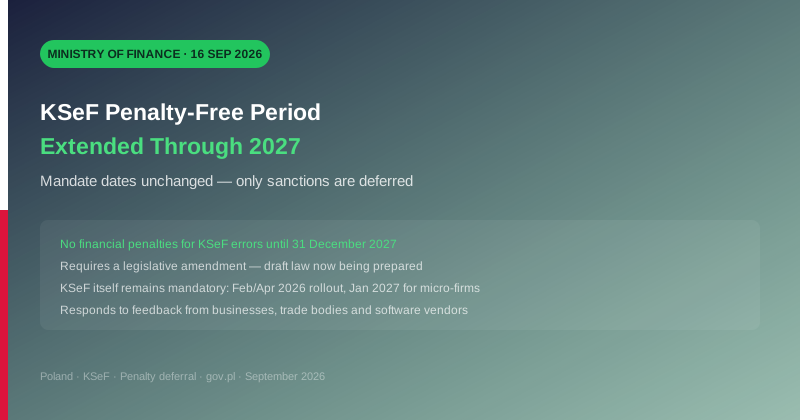
Poland's Ministry of Finance announced on 16 September 2026 that it intends to extend the deferral of financial penalties for KSeF errors to 31 December 2027 — a one-year extension that requires a legislative amendment but does not change the underlying mandate dates.
Poland's Ministry of Finance (Ministerstwo Finansów) announced on 16 September 2026 that it intends to extend the transitional period during which businesses will not face financial penalties for errors made while using the Krajowy System e-Faktur (KSeF), Poland's mandatory national e-invoicing system. Under the proposal, the penalty deferral would run through 31 December 2027, effectively pushing the start of enforceable sanctions to 1 January 2028.
What Is Actually Changing
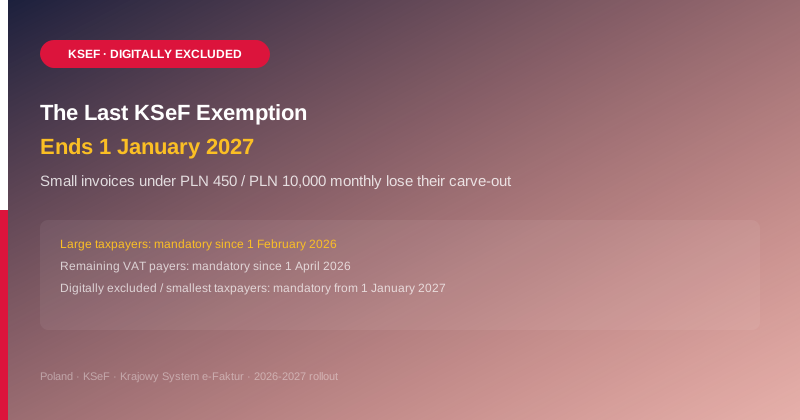
This is a change to enforcement, not to the mandate itself. KSeF became mandatory for large taxpayers (turnover above PLN 200 million) on 1 February 2026, extended to most other VAT-registered businesses on 1 April 2026, and is scheduled to become mandatory for the smallest taxpayers on 1 January 2027. None of those dates move. What changes is that, for at least another year, the tax administration will not impose the specific financial penalties tied to invoicing errors and technical non-compliance under KSeF while businesses continue adapting their systems and processes.
Why the Ministry Is Doing This
The Ministry said the extension responds directly to feedback from businesses, trade organizations, tax advisers, and accounting software providers gathered during the phased rollout. Smaller businesses in particular — whose transitional arrangements expire at the end of 2026 ahead of their own 1 January 2027 mandatory start date — were cited as needing more runway to become familiar with KSeF's technical requirements (structured invoice formats, the KSeF reference number, and correction workflows) without the immediate risk of financial sanctions for good-faith mistakes.
What Still Needs to Happen
The Ministry was explicit that extending the deferral to the end of 2027 requires a legislative amendment, and confirmed that work on the relevant draft law is only now beginning. Until that amendment is passed, the current legal deferral period remains in place. Businesses should treat the 2027 extension as the Ministry's stated intention rather than settled law, and continue building toward full KSeF compliance rather than treating the penalty holiday as a reason to delay implementation.
Source
Polish Ministry of Finance, "Przedłużenie odroczenia kar za błędy w stosowaniu KSeF do końca 2027 r.", 16 September 2026: gov.pl/web/finanse.